Contract intelligence
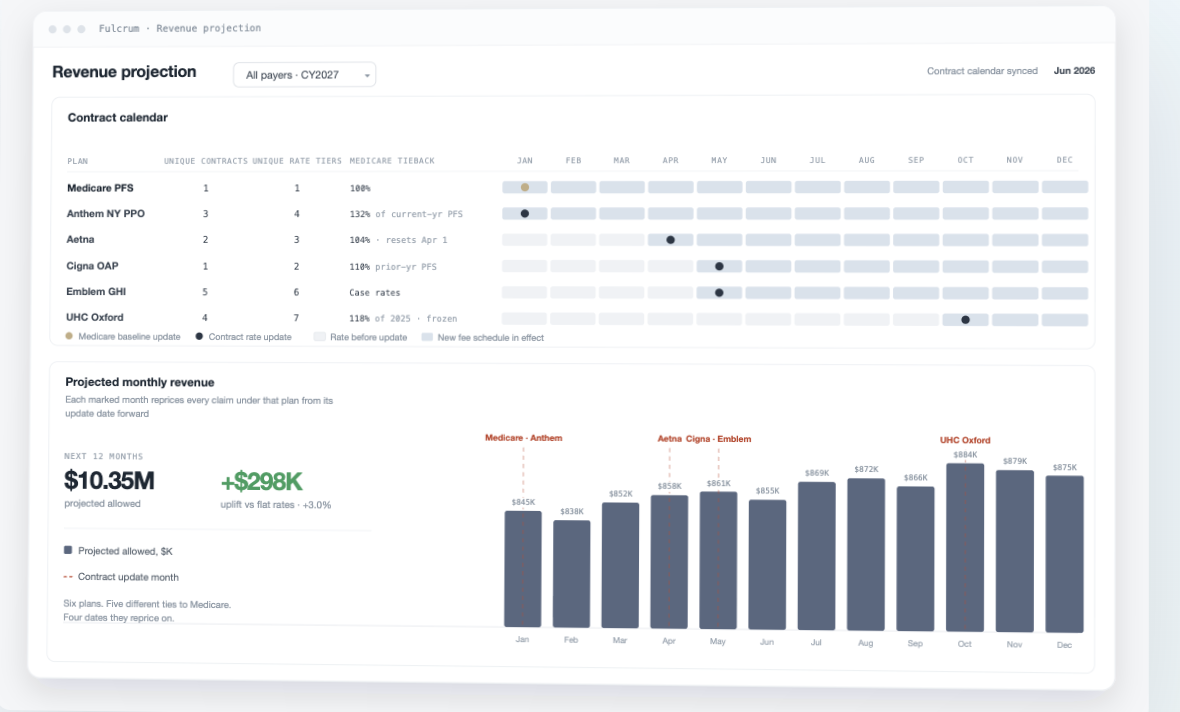
Structure payer products, fee schedules, Medicare tiebacks, and effective dates in one usable model.
 Contact us
Practice financial intelligence
See how every contract, payment, and service line performs. See how visits, endoscopy, laryngoscopy, in-office procedures, and surgery perform across every payer product.
Financial visibility for Otolaryngology (ENT)
Fulcrum structures product-level rates and reimbursement rules across office and facility settings, then applies them to the services your ENT practice actually performs.
One connected intelligence layer
Structure payer products, fee schedules, Medicare tiebacks, and effective dates in one usable model.
Detect and investigate potential underpayments in an automated, accurate way.
Test proposed rates against actual volume and bring clear evidence into payer conversations.
Integrate encounter and cost data to see precise unit economics for specific CPT codes.
What becomes answerable
CY 2027 proposed PFS
How the proposed rule translates into revenue impact for you depends on your service mix, volume, locality, and your commercial contracts' relationship to Medicare updates.
CMS's own reconciliation table (Table D-B5) puts otolaryngology (ENT) at -8.1% for 2027. That figure is the specialty-wide, volume-weighted change in total RVU-based allowed charges: the aggregate gain or loss across every code the specialty bills, before the separate conversion-factor cut. Our reconstruction agrees closely at -9.2%, a net reduction of $110 million in national allowed charges.
Otolaryngology (ENT) bills about 82% of its Medicare dollars in the office (non-facility) setting. By site of service, the 2027 change splits as follows:
| Site of service | Change | Allowed $ |
|---|---|---|
| Office (non-facility) | -10.4% | -$101M |
| Facility | -3.9% | -$8M |
All figures are national, hold 2025 utilization fixed, and exclude the separate 1.68% conversion-factor cut.
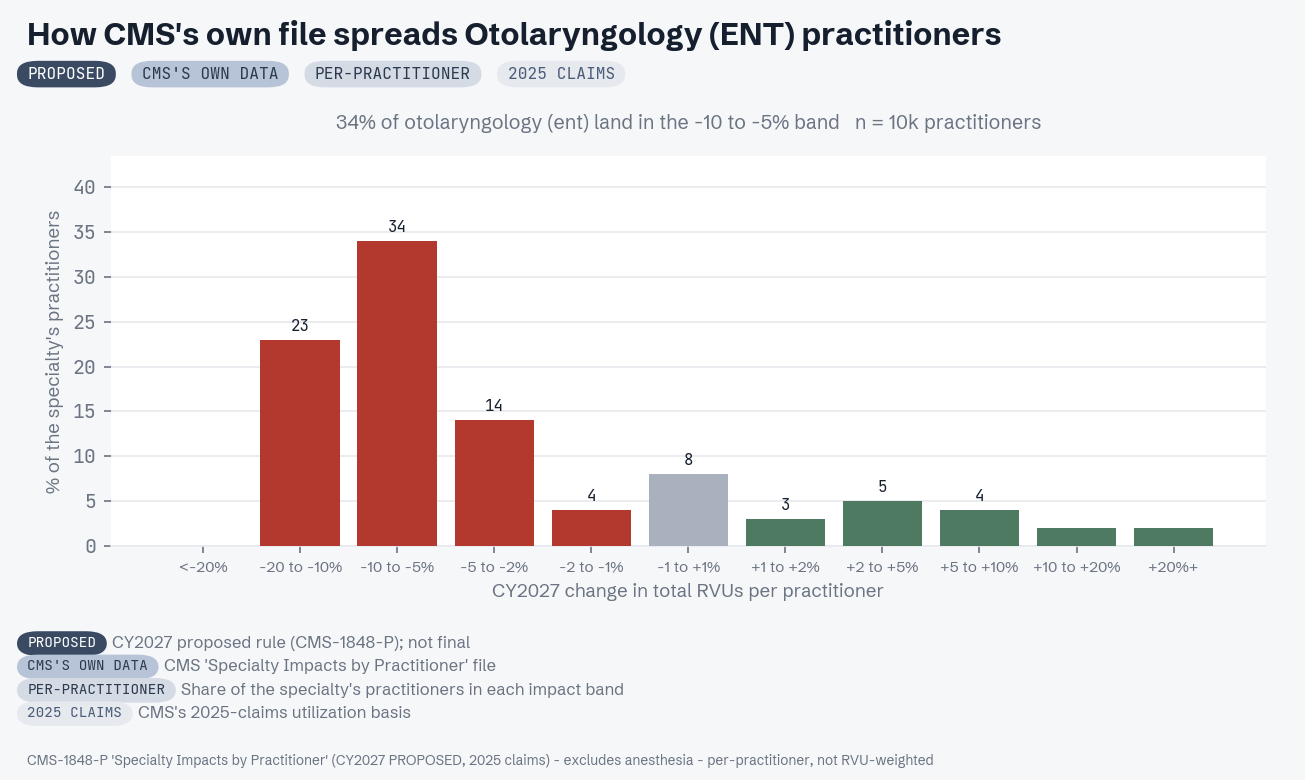
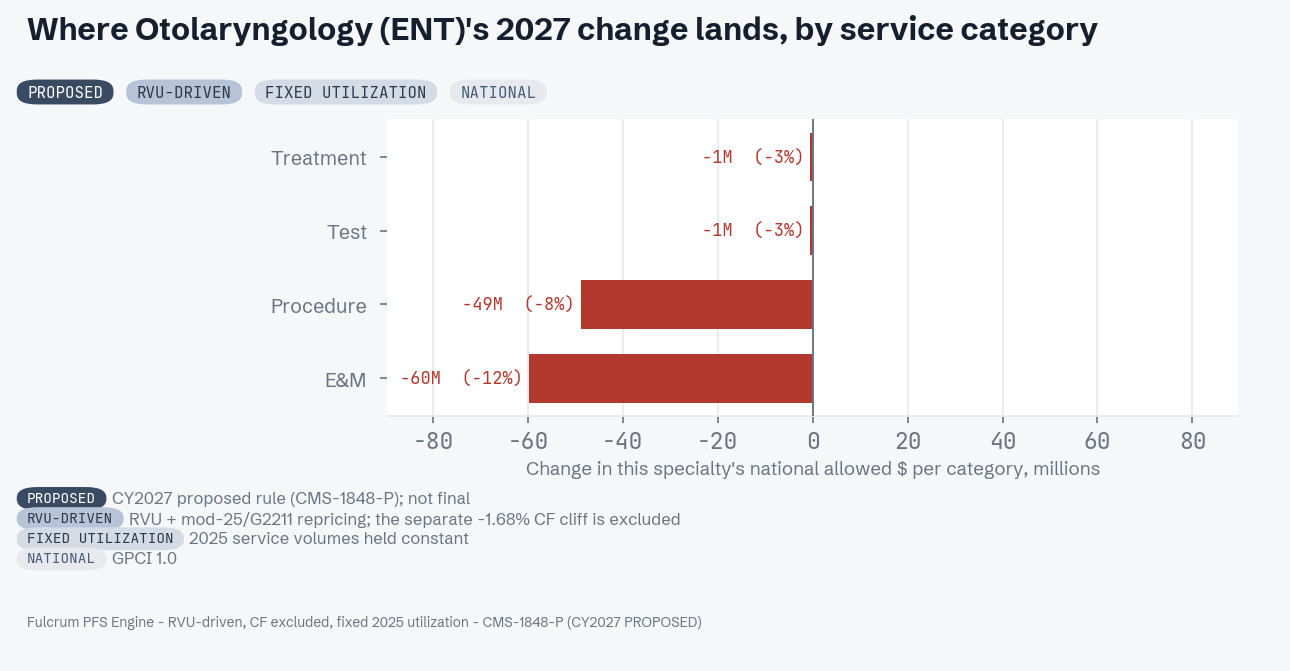
The specialty average hides a wide spread, and CMS's own practitioner-level file proves it. 34% of otolaryngology (ENT) practitioners land in the -10 to -5% band, and about 71% see a cut deeper than 2%. Where a practice lands is a question of service mix: the otolaryngology (ENT) practices hit hardest are those with the most same-day office procedures billed with a visit (laryngoscopy, nasal endoscopy, cerumen removal).
Practice-specific analysis
Start with one contract, one fee-schedule question, or an ongoing view across the practice.